Affordable Homeownership in Kenya: The 2026 Guide to Subsidised Mortgages, Sectional Units, and Buyer Reliefs
The 2026 definitive guide to affordable homeownership in Kenya. Learn how KMRC single-digit mortgages, Affordable Housing Program tax reliefs, and modern sectional apartments unlock accessible home buying.
Redefining the Kenyan Dream of Homeownership
For decades, homeownership in urban Kenya was largely an elite privilege. Commercial bank mortgage rates hovered between 14% and 18%, down payment demands were steep, and property prices in central Nairobi escalated beyond the reach of median salary earners.
Today, a transformative shift is underway. Through the combined impact of the Affordable Housing Act 2024, the Kenya Mortgage Refinance Company (KMRC), and private developers delivering high-efficiency sectional units, affordable homeownership is becoming an achievable reality for young professionals and growing families.
The KMRC Paradigm Shift
By providing participating lenders with wholesale liquidity at 5%, KMRC has enabled commercial banks and SACCOs to cap primary residential mortgages at 9.5%, slashing monthly debt service costs by over 30% compared to traditional commercial loans.
Understanding the Financial Pillars of Affordable Housing
Modern affordable homeownership in Kenya rests on three distinct pillars:
1. KMRC Single-Digit Mortgages: Fixed-rate loans (9.5% - 10.5%) with repayment tenures up to 20 to 25 years for properties priced up to KSh 10.5 million.
2. Boma Yangu / State AHP Initiatives: Public-private partnership developments offering subsidized studios, 1-bedroom, and 2-bedroom units under tenant-purchase schemes.
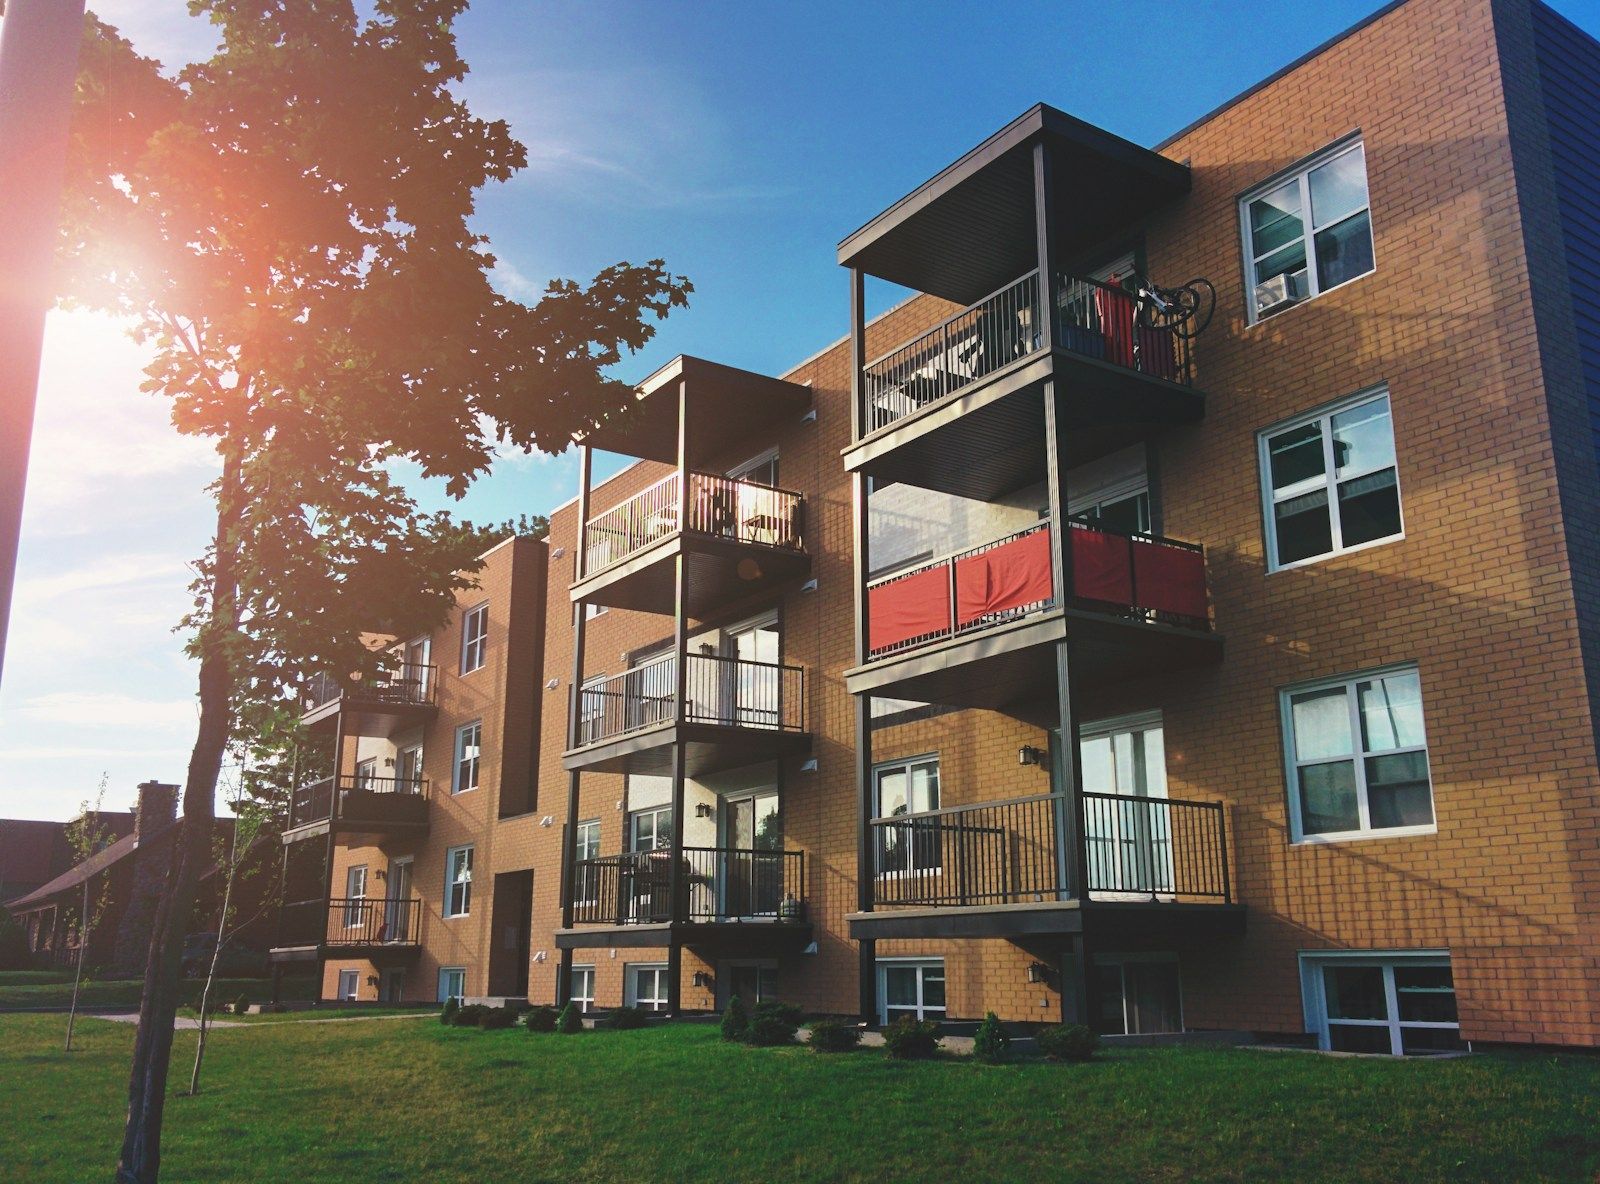
3. Private Sector Sectional Developments: Private developers creating high-quality, compact sectional apartments in well-connected commuter nodes (such as Rongai, Ruaka, and Kikuyu) priced from KSh 4.5M to KSh 8.5M.
Commercial Mortgage vs KMRC-Subsidised Loan Comparison
Consider a residential purchase of a 2-bedroom apartment priced at KSh 7,500,000 with a 20% deposit (KSh 1,500,000) and a KSh 6,000,000 loan over 20 years:
| Financing Metric | Standard Commercial Bank Mortgage | KMRC-Backed Single-Digit Mortgage | Monthly & Total Savings |
|---|---|---|---|
| Interest Rate | 16.5% Variable | 9.5% Fixed | 7.0% lower annual interest rate |
| Monthly Repayment | KSh 85,600 | KSh 55,900 | Saves KSh 29,700 every month |
| Total Interest Paid (20 Yrs) | KSh 14,544,000 | KSh 7,416,000 | Saves KSh 7,128,000 over full loan |
| Qualifying Monthly Net Income | Min KSh 220,000 | Min KSh 145,000 | Significantly expands borrower eligibility |
Maximising First-Time Buyer Tax Reliefs
Kenyan tax law provides valuable incentives to reduce the financial load on new homebuyers:
- Mortgage Interest Deduction (MID): Under Section 15 of the Income Tax Act, you can deduct up to KSh 300,000 per year (KSh 25,000 monthly) in mortgage interest from your taxable employment income, generating substantial PAYE tax refunds.
- Affordable Housing Tax Relief: Earners contributing to approved home purchase savings schemes enjoy a 15% tax rebate on annual contributions up to KSh 108,000.
- Stamp Duty Relief: First-time purchasers acquiring homes under designated state affordable housing frameworks are exempt from the standard 4% urban Stamp Duty.
Check Your SACCO Membership
Many SACCOs (such as Stima SACCO and Kenya Police SACCO) offer faster loan processing and lower ancillary fees for KMRC-backed mortgages than commercial banks. If you are a member of a regulated SACCO, explore their asset financing products first.
Where to Find Quality Affordable Units in Nairobi
The private market offers compelling modern options within commuter hubs:
- [Ongata Rongai Corridor](/locations/ongata-rongai): With the expanded Langata Road and upcoming rail commuter links, projects like Magenche Residences provide contemporary 2-bedroom apartments from KSh 5.0M, offering superior square footage at accessible price points.
- Ruaka and Kiambu Road Fringe: High-amenity suburban nodes providing modern 1 and 2-bedroom units close to Two Rivers and the Northern Bypass.
- Kikuyu and Waiyaki Way Expansion: Direct access to Westlands within 25 minutes via the modernized highway corridor, featuring entry-level apartments from KSh 4.2M.
Affordable Housing Benchmarks
Key Takeaways
- 01.KMRC refinancing caps mortgage rates at 9.5%, reducing monthly loan payments by nearly 35% compared to commercial rates.
- 02.Properties up to KSh 10.5M in the Nairobi Metropolitan Area qualify for single-digit financing.
- 03.Take full advantage of the KSh 300,000 annual Mortgage Interest Deduction to lower your PAYE tax burden.
- 04.Private market developments in commuter corridors like Ongata Rongai offer modern, high-quality living within affordable budgets.
Find Your Pathway to Homeownership with Zuri Estates
At Zuri Estates, we believe quality housing should be within reach. We partner with vetted developers and KMRC-participating lenders to structure accessible homeownership solutions tailored to your income.
Explore our affordable residential developments or schedule an advisory consultation to evaluate your financing options.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
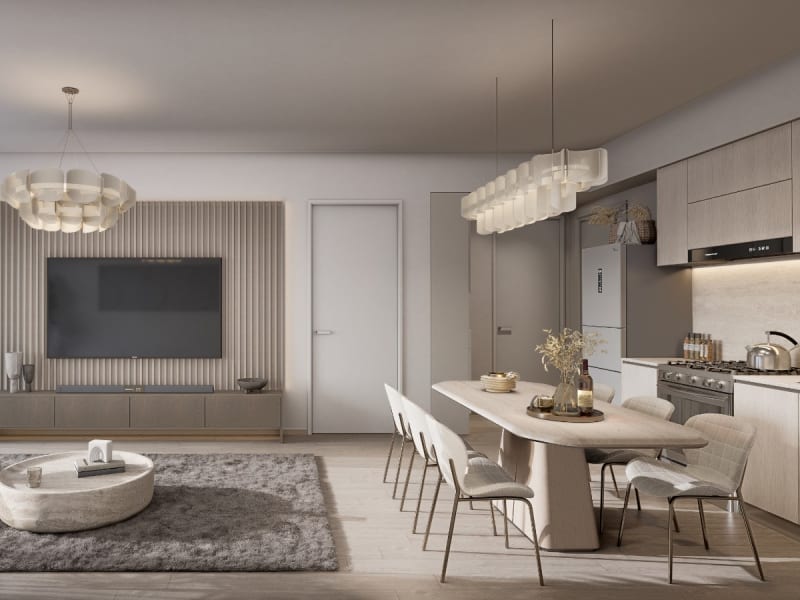
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Featured Neighbourhood
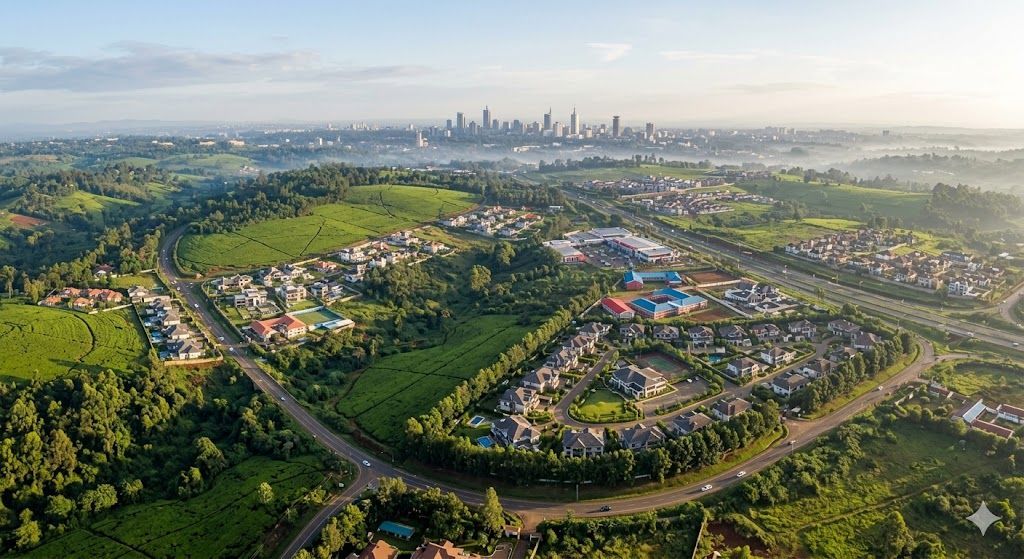
Ongata Rongai
Affordable Family Living with Nairobi Convenience
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.