Buying an Off-Plan Apartment in Kenya: The Complete Risk, Contract, and Due Diligence Guide
Off-plan property buying in Kenya offers attractive entry pricing and staggered payment terms, but carries serious completion and contract risks. Here is the definitive guide to protecting your capital, complete with a 25-point due diligence checklist.
The commercial appeal of off-plan property buying in Kenya is undeniable. In dynamic residential nodes like Kilimani, Westlands, and Kileleshwa, committing to an apartment at groundbreaking allows you to secure an asset at entry-level pre-sale pricing, often 15 percent to 25 percent below the eventual market value of a completed ready property.
Furthermore, off-plan acquisitions eliminate the crushing burden of commercial bank mortgage interest rates. Instead of borrowing at 16 percent to 18 percent variable interest, an off-plan buyer funds their acquisition through structured, interest-free construction instalments spread over two to three years.
However, off-plan purchasing carries genuine commercial and structural risk. When you buy off-plan, you are purchasing a promise: an agreement that a corporate developer will coordinate architects, engineers, contractors, and statutory regulators to deliver a high-quality building on schedule. If that promise falters, your capital can become trapped in a delayed or stalled project.
This comprehensive guide provides an exhaustive roadmap to navigating off-plan property acquisitions in Kenya safely, complete with an actionable 25-point due diligence checklist to protect your investment.
Key Takeaways
- 01.Off-plan acquisitions offer substantial price discounts and interest-free instalment terms, but carry completion and execution risks.
- 02.Your legal relationship with the developer is strictly governed by the written Agreement for Sale, not promotional sales brochures or verbal promises.
- 03.Insist on a fixed-price contract with zero price escalation clauses, explicit completion dates, and enforceable delay compensation penalties.
- 04.Link your instalment payments to verified architectural construction milestones certified by an independent professional, rather than arbitrary calendar dates.
- 05.Execute our 25-point off-plan due diligence checklist prior to signing any binding Letter of Offer or paying reservation deposits.
1. The Three Pillars of Off-Plan Safety
A successful off-plan acquisition rests on three non-negotiable structural pillars:
| Pillar | Core Objective | How to Enforce It | Critical Failure Risk |
|---|---|---|---|
| 1. Legal Due Diligence | Confirming clean land title, unencumbered lease terms, and full County and NEMA approvals | Official land search on ArdhiSasa, green card inspection, certified approved architectural drawings | Purchasing into a development that faces demolition or stop-work orders due to zoning or riparian violations |
| 2. Financial Governance | Safeguarding buyer deposit funds against developer insolvency or capital diversion | Deposit held in stakeholder escrow account released only upon certified structural milestones | Developer uses your deposit to clear debts on older projects, stalling your building when cash runs dry |
| 3. Contractual Precision | Binding the developer to fixed prices, exact finishes, completion dates, and defect liabilities | Comprehensive Agreement for Sale drafted with advocate review, including liquidated damages for delay | Developer delivers building 2 years late with lower-grade substitute finishes, and zero compensation |
2. Milestone-Based Payments Versus Calendar-Based Schedules
The single most important contractual safeguard in an off-plan purchase is milestone-linked financing.
Unscrupulous or poorly capitalized developers frequently propose calendar-based payment schedules: e.g. 'Pay 10% on signing, 10% every three months.' Under this arrangement, if construction completely freezes for six months due to contractor disputes, the developer will still demand payment on the scheduled dates.
You must insist that your Agreement for Sale links every installment directly to certified structural milestones on site:
Milestone-Linked Payment Schedule
A contractual payment framework where installment disbursements are triggered exclusively upon presentation of a formal certificate issued by an independent registered consulting architect or quantity surveyor confirming completion of specific structural stages.
Typical Off-Plan Milestone Payment Structure
A balanced milestone schedule typically reflects:
* Milestone 1 (10% - 20%): Signing of the Agreement for Sale (held in stakeholder escrow).
* Milestone 2 (15%): Completion of basement excavation, shoring piles, and casting of the ground floor slab.
* Milestone 3 (15%): Casting of mid-level structural floor slabs (e.g. Level 10 of a 20-storey tower).
* Milestone 4 (15%): Superstructure roof slab topping out.
* Milestone 5 (15%): Completion of external masonry walling, window glazing, and primary MEP rough-ins.
* Milestone 6 (15%): Completion of internal plastering, floor tiling, cabinetry joinery, and sanitary fit-out.
* Milestone 7 (10%): Issuance of the County Certificate of Occupancy, joint snagging sign-off, and Sectional Title handover.
3. Essential Contractual Clauses to Negotiate
Your conveyancing advocate must carefully examine the Agreement for Sale for four vital protections:
1. Fixed-Price Guarantee: Explicit confirmation that the agreed purchase price is total, inclusive of parking and finishes, and cannot be increased due to inflation, material costs, or currency movements.
2. Liquidated Damages for Delayed Handover: If the developer exceeds the agreed completion date beyond a reasonable grace period (typically 3 to 6 months for force majeure events), the developer must pay the purchaser an agreed monthly penalty matching market rental value.
3. Defects Liability Period (DLP): A minimum 6-month (ideally 12-month) post-handover period during which the contractor rectifies any building defects at zero cost to the buyer.
4. Termination and Refund Remedies: If the developer stalls construction completely for an extended period (e.g. 180 continuous days), the buyer must retain the contractual right to terminate the agreement and recover all paid funds with commercial interest.
Watch Out for One-Sided Clauses
Many standard developer contracts contain steep penalties if a buyer delays a payment by 7 days, but provide zero penalties if the developer delays completion by two years. Ensure your advocate balances these remedies before signing.
4. The 25-Point Off-Plan Due Diligence Checklist
Before committing your capital to any off-plan development in Kenya, complete this rigorous 25-point verification audit with your advocate:
| # | Verification Checkpoint | Required Evidence / Document | Status |
|---|---|---|---|
| 01 | Developer Legal Identity | BRS official corporate CR12 search confirming active directors | Mandatory |
| 02 | Land Title Ownership | Ministry of Lands search confirming clean title in developer name | Mandatory |
| 03 | Land Encumbrances | Search confirming any bank charges against the mother parcel | Mandatory |
| 04 | Bank Undertaking | Letter of Undertaking for partial sectional title discharge | If Charged |
| 05 | County Planning Approval | Certified architectural drawings stamped by Nairobi City County | Mandatory |
| 06 | NEMA EIA License | Valid Environmental Impact Assessment license from NEMA | Mandatory |
| 07 | NCA Project Registration | National Construction Authority site compliance certificate | Mandatory |
| 08 | Main Contractor License | NCA Category 1 or 2 active contractor practicing license | Mandatory |
| 09 | Lead Architect Registration | Active BORAQS registration certificate of the consulting architect | Mandatory |
| 10 | Structural Engineer License | Active EBK registration certificate of the structural engineer | Mandatory |
| 11 | Water Authority Permit | Water Resources Authority (WRA) borehole abstraction permit | Mandatory |
| 12 | Escrow Stakeholder Account | Stakeholder agreement with designated client escrow bank account | Mandatory |
| 13 | Milestone Payment Schedule | Written schedule linking payments to certified physical progress | Mandatory |
| 14 | Fixed-Price Clause | Explicit clause barring future price escalation | Mandatory |
| 15 | Defects Liability Terms | Minimum 6-month defect rectification clause in contract | Mandatory |
| 16 | Liquidated Damages Clause | Enforceable financial penalty for unexcused completion delays | Mandatory |
| 17 | Parking Allocation | Legally deeded parking bay number marked on Sectional Plan | Mandatory |
| 18 | Specification Schedule | Itemized list of brands for sanitaryware, tiles, and joinery | Mandatory |
| 19 | Full-Load Backup Generator | Contractual confirmation of full power backup inside apartments | Mandatory |
| 20 | Borehole Filtration Plant | Technical confirmation of on-site Reverse Osmosis filtration | Mandatory |
| 21 | Lift-to-Unit Ratio | Adequate passenger and service lift provision on tower plans | Mandatory |
| 22 | Service Charge Estimate | Itemized breakdown of projected annual common property expenses | Mandatory |
| 23 | Dispute Resolution Clause | Arbitration clause under the Chartered Institute of Arbitrators | Mandatory |
| 24 | Past Project Inspection | Physical visit to developer previous completed developments | Mandatory |
| 25 | Independent Legal Review | Formal review of all documents by purchaser own advocate | Mandatory |
Navigate Off-Plan Property Safely with Zuri Estates
At Zuri Estates, we believe that off-plan buying can be one of the most rewarding wealth creation strategies in East Africa, provided it is executed with uncompromising discipline.
We curate only verified developments backed by reputable development consortia, clean titles, full statutory approvals, and transparent escrow frameworks across Kilimani, Westlands, Kileleshwa, and Lavington.
Explore our current collection of verified off-plan developments, or connect with our property advisory team to discuss your off-plan acquisition strategy with complete peace of mind.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Kilimani · Riara Road, Opposite The Junction Mall, Kilimani, Nairobi
Golden Apple Residence
Kilimani's Urban Benchmark: Twin-Tower Sophistication Directly Opposite The Junction Mall

Westlands · Ring Road, Opposite The Oval, Westlands, Nairobi
Hephé Palace
Nairobi's Dual-Horizon Crown: Where 25 Storeys of Architectural Mastery Meet Karura Forest Serenity
Kilimani · Kirichwa Road, Kilimani, Nairobi, Kenya
Ivy Park Residence
Elevated Living, Exceptional Investment in Kilimani
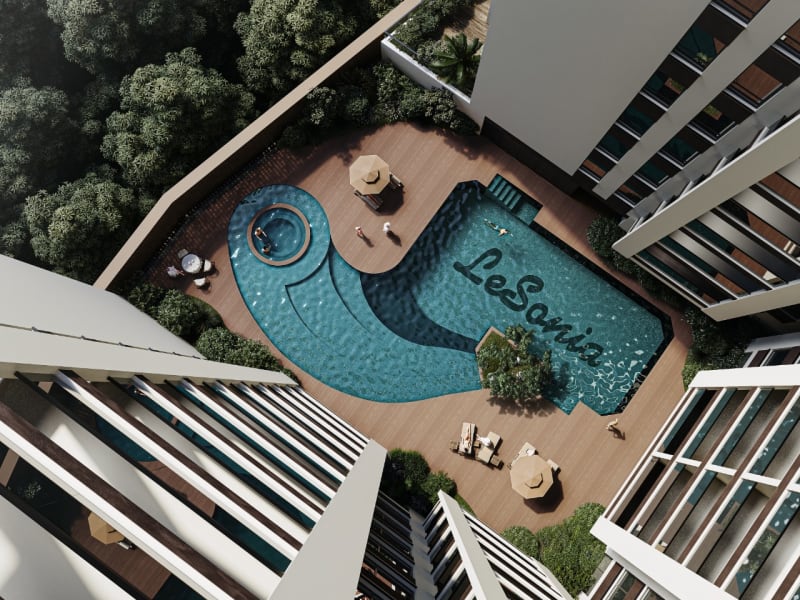
Kileleshwa · Intersection of Gatundu Road & Tinderet Avenue, Kileleshwa, Nairobi
Lesonia Residency
Contemporary Balcony-Garden Living in Prime Kileleshwa
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.