How to Check a Property Developer in Kenya Before Paying a Deposit
A polished 3D render and a billboard on a prime road do not prove a developer can deliver. Here is how to audit corporate registration, contractor accreditation, escrow protections, and previous track records before paying a shilling.
A billboard standing along an arterial road in Nairobi can make any project look institutional. High-gloss 3D architectural visualisations, drone footage sweeping over the city canopy, and a launch cocktail party can project immense financial strength. Yet behind that marketing facade, an off-plan property purchase is fundamentally a long-term unsecured financial commitment.
When you commit a deposit of KES 2 Million, KES 5 Million, or KES 15 Million to a new residential development, you are not merely purchasing real estate. You are extending credit to a corporate entity, trusting that its management consortium has the liquidity, engineering capability, regulatory approvals, and integrity to transform a plot of red soil into a habitable, legally titled asset.
Whether you are an executive purchasing a home in Westlands, a family upgrading to a modern residence in Kilimani, or a Kenyan in the diaspora sending hard-earned savings from London, Dubai, or Toronto, this guide details the exact investigative due diligence protocol required to evaluate a property developer in Kenya before releasing funds.
Key Takeaways
- 01.Never confuse a polished sales brochure or showroom with corporate financial capacity and construction competence.
- 02.Always conduct an official corporate search via the Business Registration Service (BRS) to uncover the developer true beneficial ownership and existing bank charges.
- 03.Confirm that both the main contractor and the project hold active licenses and compliance certificates from the National Construction Authority (NCA).
- 04.Insist that your purchase deposit is held in a stakeholder escrow account governed by written professional milestones, rather than a general operating pool.
- 05.Inspect the developer previous completed projects in person to evaluate build longevity, ongoing facility management, and title issuance track records.
1. Corporate Identity and Beneficial Ownership Verification
The first step in checking any developer is establishing the legal entity behind the sales desk. In Kenya, property developments are almost universally executed through a Special Purpose Vehicle (SPV), typically a private limited liability company established solely for that single project.
While an SPV structure is standard commercial practice to ring-fence project risk, it also means the entity you are contracting with may possess zero assets beyond the specific plot of land. If the development fails, claiming recourse against the parent company can be legally complex if corporate boundaries are not clearly defined.
Special Purpose Vehicle (SPV)
A dedicated private limited company incorporated exclusively to acquire land, construct, finance, and sell a single property project, shielding the developer wider corporate assets from project-specific liabilities.
To evaluate the corporate entity, your conveyancing advocate must perform an official corporate search through the Business Registration Service (BRS) via the eCitizen platform. This search extracts the official CR12 document, which confirms:
* Incorporation Date and Active Status: Whether the company is legally compliant, currently in good standing, or facing pending strike-off notices.
* Full List of Directors and Beneficial Owners: The real individuals behind the corporate vehicle, allowing you to check their commercial reputation and executive background in Kenya.
* Registered Company Charges and Debentures: Whether the developer has charged its corporate assets, future receivables, or project shares to commercial banks or private mezzanine lenders.
Unregistered Foreign Entities
If a developer markets itself under a glamorous international brand name, verify that the local Kenyan SPV signing your Agreement for Sale is formally connected to that parent company. Never sign a contract with an unregistered overseas entity that maintains no legal presence or physical assets within Kenyan jurisdiction.
2. Auditing Construction Accreditations and Professional Consultants
In Kenya's building sector, a developer is an economic promoter, not necessarily a builder. The physical execution of the multi-storey towers lining neighbourhoods like Kileleshwa and Lavington is carried out by the main contractor and overseen by licensed consulting professionals.
A reputable developer will openly disclose its entire professional consortium in the pre-sale disclosure package. You should systematically verify each entity across Kenya's statutory registration bodies:
| Professional Body | Statutory Role | Public Verification Method | Key Red Flag to Watch For |
|---|---|---|---|
| National Construction Authority (NCA) | Registers and classifies contractors from Category NCA 1 to NCA 8 | NCA online contractor register portal | Contractor operating with an expired annual practicing license |
| Board of Registration of Architects and Quantity Surveyors (BORAQS) | Regulates lead consulting architects and quantity surveyors | BORAQS gazetted register of active architects | Architectural plans drawn by unregistered draughtsmen without seal |
| Engineers Board of Kenya (EBK) | Licenses structural, civil, and MEP consulting engineers | EBK register of professional engineers | Lack of certified structural calculations for high-rise towers |
| National Environment Management Authority (NEMA) | Issues environmental impact assessment (EIA) licenses | NEMA public licensing database | Commencing excavation before EIA license gazettement |
For modern high-rise developments of 15 to 25 storeys, such as Hephé Palace in Westlands or Golden Apple Residence in Kilimani, the main contractor should ideally hold an NCA 1 classification, denoting unlimited financial capacity and verified competence in executing large-scale structural reinforced concrete.
3. Title Verification and Bank Charge Transparency
A developer cannot sell you rights in real estate that they do not legally own or control. Before paying any reservation fee, your advocate must confirm the status of the development mother title through official land registry searches on the Ministry of Lands ArdhiSasa portal or manual registry files for unregistered parcels.
Equally important is discovering whether the developer has taken a construction loan against the mother parcel. Bank financing is common and legitimate, as it ensures the developer has sufficient working capital to complete the superstructure. However, it introduces a specific procedural requirement:
Your advocate must secure a formal Letter of Undertaking and Partial Discharge from the lending bank before you pay your deposit. This legal document guarantees that upon paying your full agreed purchase price, the lending bank will release its charge over your specific apartment unit and allow your individual Sectional Title Deed to be registered unencumbered.
Key Due Diligence Metrics for Kenyan Developments
4. Financial Structure: Escrow Accounts Versus Operating Funds
The most dangerous financial mistake a buyer can make is paying deposit instalments directly into a developer general operational bank account. In under-capitalised projects, developers frequently use deposits collected from Phase 2 buyers to pay overdue contractors on Phase 1, creating a precarious cash-flow structure.
In a well-governed project, your funds are safeguarded through an established escrow arrangement. Deposits are paid into a dedicated project bank account managed jointly by the developer legal team and an independent banking institution, or held in stakeholder capacity by a reputable law firm.
Funds are released to the developer in tranches only when an independent consulting architect or quantity surveyor certifies that specific construction milestones have been completed, such as:
* Completion of basement excavation, shoring, and foundation raft piling.
* Casting of the ground floor podium slab.
* Casting of structural floors up to level 10, level 15, and rooftop superstructure.
* Completion of masonry walling, window glazing, and primary MEP rough-ins.
* Final internal joinery, floor tiling, and sanitary fit-out.
Stakeholder Capacity Clause
Ensure your Agreement for Sale specifies that the law firm receiving your deposit holds the funds as 'Stakeholders' rather than 'Agents for the Vendor'. A stakeholder owes fiduciary duties to both parties and cannot release funds to the builder without contractual milestone verification.
5. In-Person Track Record Inspection: Inspecting Past Phases
Past delivery is the single strongest indicator of future performance. While first-time developers can certainly deliver quality buildings, partnering with an experienced development consortium significantly mitigates project delivery risks.
Do not settle for a list of project names on a glossy brochure. Take a Saturday morning to physically visit developments completed by the same developer 2, 4, or 6 years ago. Once on site, inspect the physical reality of the building:
* Facade Weathering and Paint: Has the exterior facade cracked, peeled, or stained heavily from monsoon rains, or did the developer invest in durable silicone-based textured coatings?
* Lifts and Mechanical Plant: Are all passenger lifts operational, or is one permanently broken down? Ask who the lift supplier and maintenance contractor are.
* Borehole and Water Quality: Is the water clear and soft, or does it carry a saline smell that corrodes brass tapware and shower mixers?
* Title Issuance: Speak discreetly to existing homeowners in the lobby. Ask them directly: 'Have you received your individual Sectional Title Deed from the Ministry of Lands, and how long did the conversion take after practical handover?'
6. The Developer Vetting Checklist: Questions to Ask Before Signing
Before you sign a Letter of Offer or instruct your advocate to review an Agreement for Sale, present the developer sales team with the following direct questions. A transparent, well-capitalised developer will provide documented answers without hesitation:
1. What is the registered corporate name and registration number of the project SPV?
2. Who is the registered main contractor, and what is their current NCA category license number?
3. Can you provide certified copies of the approved architectural and structural drawings stamped by Nairobi City County?
4. Has NEMA issued an Environmental Impact Assessment (EIA) license for this specific development?
5. Is the land freehold or leasehold, and what is the unexpired lease term remaining on the mother grant?
6. Is the mother title charged to any commercial bank, and will the bank provide a Letter of Undertaking for individual sectional title discharge?
7. Which law firm acts as stakeholder for purchaser deposit funds, and under what release milestones are funds disbursed?
8. What is the contracted completion date, what grace period applies, and what liquidated damages will the developer pay if completion is delayed beyond the agreed timeline?
9. What is the length of the Defects Liability Period, and what process governs post-handover repairs?
Begin Your Property Journey with Verified Foundations
Navigating property acquisitions in Kenya does not require blind trust. It requires structured inquiry, competent legal representation, and an advisory partner who prioritises verified data over marketing hype.
At Zuri Estates, every master development and residential apartment featured on our platform undergoes preliminary document auditing, planning verification, and on-site inspection before listing. We help local professionals, diaspora investors, and international buyers identify verified properties that align with their wealth preservation goals.
Explore our curated portfolio of verified developments across Westlands, Kilimani, and Kileleshwa, or connect with our property advisory team to discuss your investment requirements with complete clarity.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
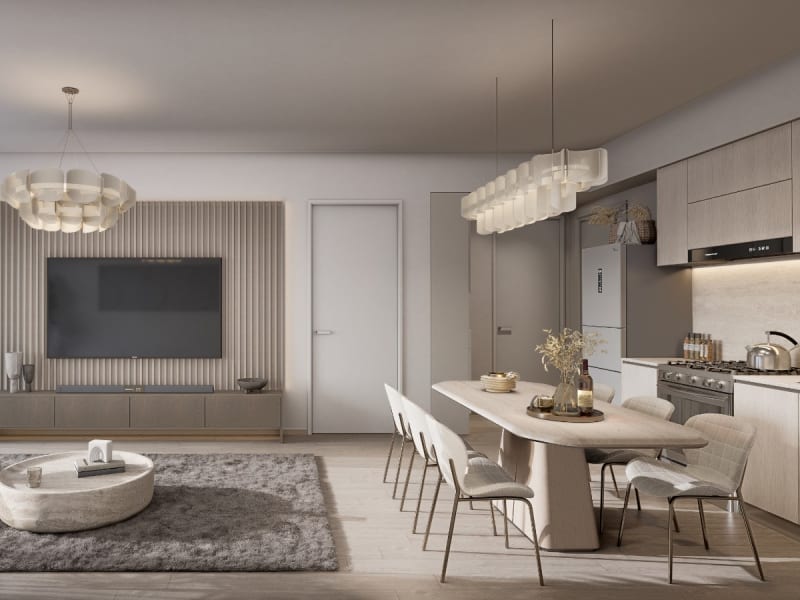
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Kilimani · Riara Road, Opposite The Junction Mall, Kilimani, Nairobi
Golden Apple Residence
Kilimani's Urban Benchmark: Twin-Tower Sophistication Directly Opposite The Junction Mall

Westlands · Ring Road, Opposite The Oval, Westlands, Nairobi
Hephé Palace
Nairobi's Dual-Horizon Crown: Where 25 Storeys of Architectural Mastery Meet Karura Forest Serenity
Kilimani · Kirichwa Road, Kilimani, Nairobi, Kenya
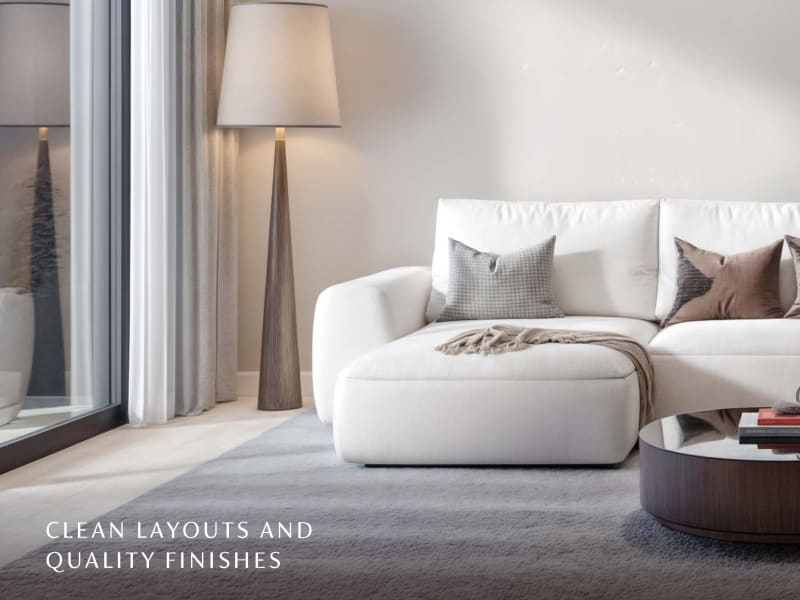
Ivy Park Residence
Elevated Living, Exceptional Investment in Kilimani
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.