Is Now the Right Time to Buy Property in Kenya? An Honest 2026 Market Timing Analysis
Should you buy property in Kenya in 2026 or wait? Analyze interest rate cycles, KMRC single-digit loans, infrastructure delivery, currency stabilization, and inflation hedging.
The Dilemma of the Hesitant Buyer
'Should I buy now, or should I wait until next year?' This question paralyzes prospective homeowners and property investors across Kenya. Buyers constantly watch for signals: Will interest rates drop? Will property prices crash? Will currency movements make homes cheaper?
While waiting on the sidelines feels cautious, in real estate, waiting carries a hidden and compounding price tag. In this 2026 market timing analysis, we examine the macroeconomic indicators, construction replacement costs, and financial math to determine whether now is the right moment to deploy capital.
The Timeless Wisdom of Real Estate
The old adage remains true: 'Don'''t wait to buy real estate. Buy real estate and wait.' In urban centers with high population growth and land scarcity, time in the market consistently beats timing the market.
The Macroeconomic Signals in 2026
Three powerful forces define the 2026 Kenyan property environment:
1. Rising Construction Replacement Costs
Property prices do not exist in a vacuum; they are anchored to the physical cost of construction materials:
- Over the past 24 months, prices for imported reinforced steel rebar, bulk Portland cement, copper electrical cabling, and architectural glazing have escalated by 12% to 18%.
- A developer breaking ground today cannot afford to sell apartments at 2022 prices. This rising replacement cost creates a firm price floor that protects existing property values from nominal price drops.
2. The Expansion of Single-Digit KMRC Mortgages
Through the Kenya Mortgage Refinance Company (KMRC), qualifying homebuyers can now access fixed 9.5% to 10.5% mortgage financing for residential properties priced up to KSh 10.5 million. This single reform has cut monthly debt service costs by over 30% compared to traditional commercial bank loans.
| Market Timing Indicator | Current 2026 Condition | Buyer Advantage / Strategy |
|---|---|---|
| Developer Pricing Power | Competitive; buyers have negotiation leverage | Negotiate 5% - 8% cash discounts or flexible milestone terms |
| Construction Input Costs | Rising (Cement, steel, imported finishes up 15%) | Lock in off-plan pricing before future developer price hikes |
| Financing Landscape | KMRC single-digit loans (9.5%) widely available | Secure fixed-rate subsidized mortgages for units under KSh 10.5M |
| Currency Exchange (USD/GBP) | Favourable for diaspora remittance earners | Deploy strong foreign currencies to acquire Shilling assets at a discount |
| Rental Demand | High in corporate nodes (Westlands, Kilimani) | Purchase income-producing units that capture immediate 8.5%+ yields |
3. Currency Advantages for Diaspora Buyers
For Kenyans living in the UK, United States, Europe, or the Gulf, foreign exchange dynamics have created an unprecedented window of purchasing power. The strengthening of hard currencies against the Kenyan Shilling allows diaspora investors to acquire prime Nairobi apartments with significantly fewer dollars, pounds, or euros than five years ago.
The True Cost of Waiting: The Rent vs Buy Math
Consider a prospective homebuyer currently paying KSh 75,000 monthly rent in Kileleshwa, contemplating whether to buy an KSh 9,000,000 two-bedroom apartment today or wait two years:
- Dead Rent Paid: Over 24 months, the buyer pays KSh 1,800,000 in unrecoverable rent to their landlord.
- Lost Capital Appreciation: At a conservative 5% annual appreciation rate, the KSh 9M apartment will cost KSh 9,922,500 in two years, an increase of KSh 922,500.
- Total Cost of Waiting Two Years: KSh 1,800,000 (rent) + KSh 922,500 (price inflation) = KSh 2,722,500 in lost financial value.
Timing Economics
When SHOULD You Wait?
The only good reason to delay buying is if your personal finances are not ready: you lack sufficient emergency savings, your employment is unstable, or you haven't saved the 8% required for closing costs. Never wait purely hoping the entire market will collapse.
Key Takeaways
- 01.Rising construction costs (cement, steel, labor) create a firm floor preventing property price drops in Nairobi.
- 02.KMRC 9.5% single-digit mortgages provide accessible, fixed-rate financing for homes up to KSh 10.5M.
- 03.The cost of waiting (dead rent plus price inflation) typically costs hesitant buyers millions of shillings.
- 04.Favourable foreign exchange rates make 2026 an ideal window for diaspora investors deploying hard currency.
Take the Next Step with Zuri Estates
At Zuri Estates, we help you make property decisions grounded in hard financial facts, not emotional speculation. Our team guides you to vetted residential opportunities with proven long-term value.
Explore our current residential listings or schedule a free consultation to evaluate your property buying readiness.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Westlands · Muthithi Road, Westlands, Nairobi, Kenya
Montbleu Residences Westlands
Elevated Living. Timeless Design. Prime Westlands Address.

Kilimani · Menelik Road, Off Ngong Road, Kilimani
Emerald Residences
Premium apartments crafted for modern city living and long-term investment.

Kileleshwa · Mandera Road, Kileleshwa, Nairobi, Kenya
Maylan Park Residence
Contemporary Living in the Heart of Kileleshwa
Featured Neighbourhood
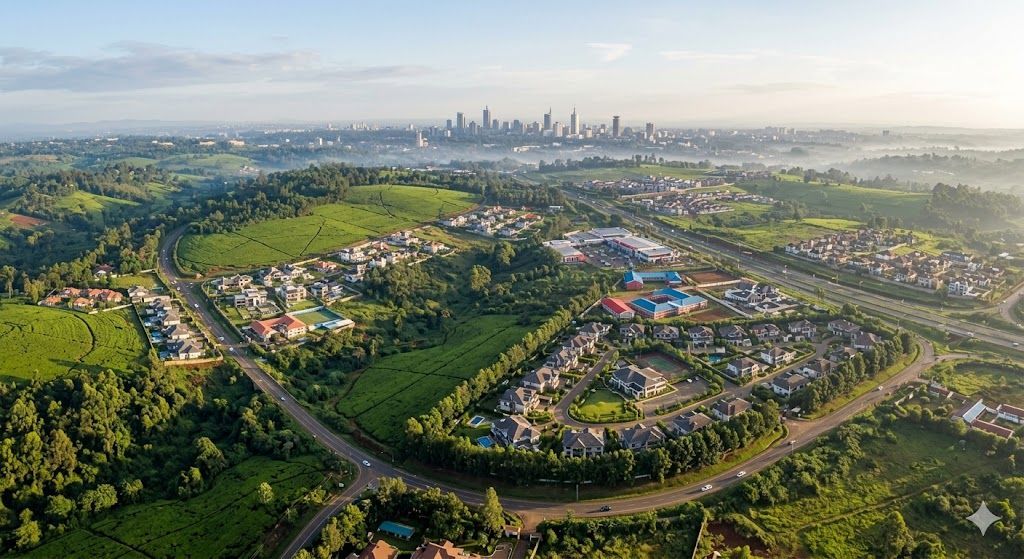
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.