Understanding KMRC: How the Kenya Mortgage Refinance Company Enables Single-Digit Home Loans
Demystify the Kenya Mortgage Refinance Company (KMRC). Discover how wholesale concessional liquidity enables 9.5% fixed-rate home loans across participating commercial banks and SACCOs.
The Breakthrough in Kenyan Housing Finance
For decades, the single greatest impediment to homeownership in Kenya was the prohibitive cost of mortgage credit. Commercial bank lending rates fluctuated wildly between 14% and 20%, tenures were short, and monthly payments exceeded the reach of working-class families. Mortgages were an elite instrument, with fewer than 30,000 active accounts in a nation of over 50 million people.
In response, the Government of Kenya, in partnership with the World Bank and the African Development Bank, established the Kenya Mortgage Refinance Company (KMRC). Today, KMRC is revolutionizing property acquisition, making single-digit, fixed-rate home loans accessible to thousands of Kenyan families.
The Wholesale Architecture
KMRC does not operate high-street bank branches. It acts as a financial liquidity pipeline, borrowing long-term concessional capital at 5% and channeling it to commercial banks and SACCOs, who lend to you at 9.5%.
How the KMRC Ecosystem Operates
The mechanism of KMRC mortgage refinancing follows four sequential steps:
1. Capital Mobilization: KMRC raises long-term funds from international development finance institutions (World Bank, IFC, AfDB) and the domestic corporate bond market at fixed low rates (around 5%).
2. Wholesale Lending to Primary Mortgage Lenders (PMLs): KMRC lends this liquidity to participating commercial banks and deposit-taking SACCOs at fixed concessional rates.
3. Retail Mortgage Disbursement: Participating lenders issue home purchase loans to qualifying citizens at capped single-digit rates (typically 9.5% fixed).
4. Refinancing and Recycling: Once the bank originates the mortgage and registers the legal charge, KMRC refinances the portfolio, replenishing the bank'''s liquidity to issue more loans.
| Feature | Commercial Bank Mortgage | KMRC-Backed Mortgage Scheme | Borrower Advantage |
|---|---|---|---|
| Interest Rate Structure | 15.0% - 18.0% Variable | 9.5% - 10.5% Fixed | 7% lower annual rate; immune to central bank hikes |
| Monthly Cost (KSh 6M Loan / 20 Yrs) | KSh 85,600 | KSh 55,900 | Saves KSh 29,700 every month |
| Maximum Property Price Cap | Unlimited (High-End) | KSh 10.5 Million (Nairobi Area) | Targeted specifically at middle-income housing |
| Maximum Household Income | No ceiling | Targeted up to KSh 150,000/mo | Designed to expand middle-class home access |
| Eligible Property Types | Any titled property | Any titled sectional apartment or house | Applies to private market and state projects |
Eligibility Criteria for KMRC Loans in 2026
To qualify for a 9.5% KMRC-subsidized mortgage through a participating lender:
- Property Price Cap: The property must be priced at or below KSh 10.5 million within the Nairobi Metropolitan Area (or KSh 8.0M in other counties).
- Valid Title Security: The property must hold an unencumbered Sectional Title Deed or Certificate of Lease registered under the Sectional Properties Act 2020 or Land Registration Act 2012.
- Down Payment: The borrower must provide a 10% to 20% equity down payment.
- Debt-to-Income Capacity: The monthly loan repayment must not exceed 40% of the applicant'''s verifiable net monthly income.
KMRC Operational Benchmarks
Participating Banks and SACCOs
Borrowers apply for KMRC loans directly through authorized primary mortgage lenders:
- Commercial Banks: KCB Bank, Co-operative Bank, Stanbic Bank, Absa Bank Kenya, NCBA, HF Group, and Credit Bank.
- Regulated SACCOs: Stima DT SACCO, Kenya Police SACCO, Harambee SACCO, Safaricom SACCO, and Imarisha SACCO.
Why SACCOs Are Leading KMRC Adoption
SACCOs frequently offer faster appraisal cycles and lower origination fees than large commercial banks. If you are already an active SACCO member, consult your credit committee regarding KMRC asset financing options.
Key Takeaways
- 01.KMRC provides wholesale liquidity that caps retail home loans at 9.5% fixed interest.
- 02.Properties priced up to KSh 10.5M in the Nairobi Metropolitan Area qualify for single-digit loans.
- 03.You apply through participating commercial banks and SACCOs, not directly to KMRC.
- 04.KMRC loans apply to any private market sectional apartment with clean title deeds.
Find KMRC-Eligible Homes with Zuri Estates
At Zuri Estates, we maintain an extensive selection of high-quality modern apartments priced within the KSh 10.5M KMRC ceiling across Kilimani, Kileleshwa, and commuter corridors.
Browse our KMRC-eligible residential listings or contact our home loan specialists to pre-qualify today.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Kajiado · Ongata Rongai – Magenche, Kenya
Magenche Residences
Ongata Rongai – Magenche

Kilimani · Menelik Road, Off Ngong Road, Kilimani
Emerald Residences
Premium apartments crafted for modern city living and long-term investment.
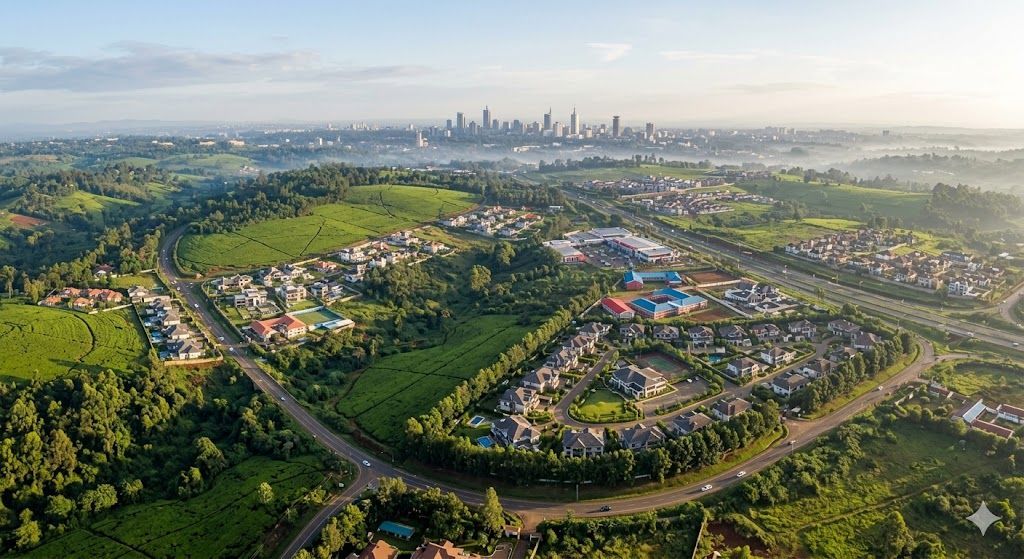
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Ongata Rongai
Affordable Family Living with Nairobi Convenience
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.