Young Real Estate Investors in Kenya: The Real Cost of Building Wealth Through Property
A realistic property wealth-building guide for young Kenyans in their 20s and 30s. Discover SACCO savings strategies, chama syndicates, KMRC subsidized loans, and avoiding speculative plot traps.
Breaking Past the Property Myth for Young Kenyans
For many young Kenyans in their 20s and 30s, real estate feels like a distant fantasy. Between rising living costs, entry-level corporate salaries, and astronomical headline prices in traditional luxury suburbs, the dream of property ownership is often dismissed as something reserved for retirement or the political elite.
Yet real estate remains the most reliable foundation for multi-generational wealth in Kenya. The secret to breaking into the market is not waiting for a massive windfall; it is understanding disciplined capital accumulation, cooperative leverage, and avoiding the speculative land traps that derail so many first-time buyers.
The Youth Wealth Strategy
You do not need KSh 20 million to begin your real estate journey. You need disciplined savings, a clean CRB credit record, and the strategic foresight to start with cash-flowing entry-level sectional assets.
The Four Modern Pathways for Young Property Investors
1. The SACCO Savings Multiplier
Cooperative savings are Kenya'''s greatest financial innovation for young professionals:
- Join a regulated deposit-taking SACCO (such as Stima DT, Safaricom, or Harambee SACCO) in your early twenties.
- Set up an automated monthly standing order saving 20% to 30% of your net income.
- After 24 to 36 months, your accumulated deposit allows you to borrow 3x to 4x your savings at 12% to 14% reducing interest, providing the exact equity needed to acquire your first property.
2. The 'Rentvesting' Strategy
Many young professionals believe their first property purchase must be their forever home. In reality, rentvesting is often mathematically superior:
- You continue renting a convenient, modest studio or 1-bed near your office in Westlands or Kilimani to eliminate commute stress.
- Meanwhile, you purchase a high-yield modern sectional apartment (such as a 2-bedroom at Magenche Residences for KSh 5.0M) in a growth corridor, renting it out to pay down the mortgage.
- Your tenant pays your debt while you build equity and capture capital appreciation.
| Strategy | Initial Capital Needed | Primary Advantage | Key Risk / Challenge |
|---|---|---|---|
| 1. SACCO Asset Loan | KSh 300k - KSh 600k savings | Low interest rates, 3x borrowing power | Requires 12-24 months of disciplined saving |
| 2. Chama Syndicate | KSh 20k - KSh 50k / month | Pooled equity, shared due diligence load | Group governance, member financial default |
| 3. KMRC Subsidized Loan | 10% - 20% down payment | Fixed 9.5% interest, 20-year repayment | Property price capped at KSh 10.5M |
| 4. Off-Plan Instalments | 20% deposit upfront | 0% interest, staged milestone cash calls | Requires strong, predictable monthly cash flow |
3. Structured Investment Chamas (Syndication)
Do not attempt to climb the property ladder alone. Form a legally registered investment chama with 4 to 8 like-minded professional colleagues:
- Draft a formal Chama Constitution through an advocate, establishing clear governance, monthly contribution rules, and voting procedures.
- Pool your capital into an interest-earning money market fund (MMF) until you accumulate the 20% deposit for a prime apartment.
- Co-own the asset under an incorporated limited liability partnership (LLP), collecting shared rental dividends.
4. Beware of the 'Cheap Plot' Speculative Trap
The single biggest financial trap for young Kenyans is buying cheap, speculative plots:
Social media is saturated with land-buying companies selling 'eighth-acre plots' 40 kilometres off the tarmac in dry bushlands for KSh 300,000, promising that 'a university and international bypass are coming.'
Reality check: These plots generate zero rental income, lack basic water and electrical grid access, suffer from fraudulent title deeds, and remain virtually impossible to sell when you need cash. Focus on cash-flowing urban sectional property instead.
Young Investor Math
Protect Your CRB Credit Score
Never allow mobile digital loan apps (M-Shwari, Tala, Fuliza) to report a default to the Credit Reference Bureau (CRB). Even a minor KSh 2,000 unresolved mobile default can disqualify you from a KSh 5 million KMRC mortgage for years.
Key Takeaways
- 01.Young professionals can enter real estate in their 20s through SACCO leverage and KMRC subsidized loans.
- 02.'Rentvesting' allows you to build property equity where numbers make sense while renting near work.
- 03.Avoid cheap, speculative rural land plots that generate zero cash flow and carry high fraud risks.
- 04.Protect your credit score: clean CRB records are essential for securing institutional property financing.
Start Your Wealth Journey with Zuri Estates
At Zuri Estates, we empower the next generation of Kenyan homeowners and investors. We offer honest guidance, verified entry-level sectional residences, and transparent payment plans.
Explore our entry-level residential opportunities or connect with a Zuri youth advisory specialist today.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
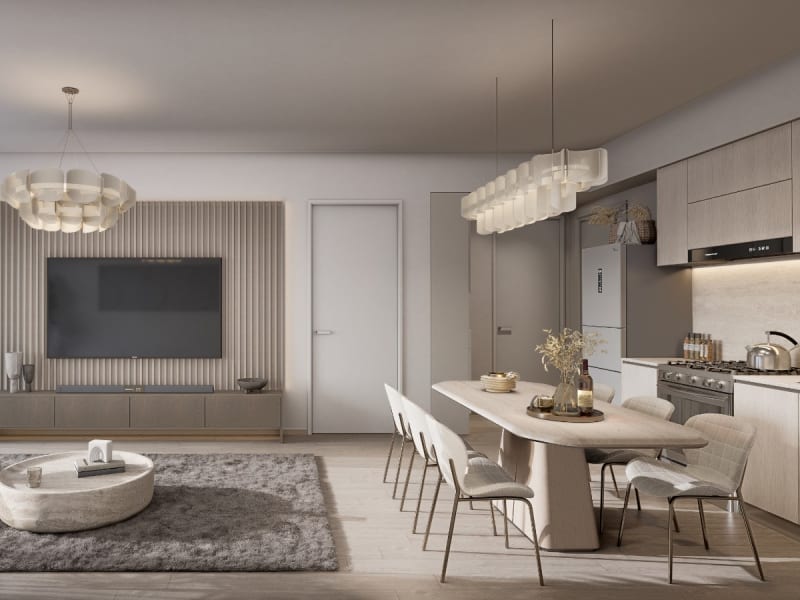
1 Bedroom Residence at Golden Apple Residence Kilimani
Calibrated 1-Bedroom Urban Suite with Deep Balcony Directly Opposite The Junction Mall

KILIMANI · RIARA ROAD, OPPOSITE THE JUNCTION MALL, KILIMANI, NAIROBI
1 Bedroom plus Study Executive Residence at Golden Apple Residence Kilimani
Generous 85 SQM Executive Suite with Dedicated Home Office Alcove Opposite The Junction Mall

Kajiado · Ongata Rongai – Magenche, Kenya
Magenche Residences
Ongata Rongai – Magenche

Kilimani · Menelik Road, Off Ngong Road, Kilimani
Emerald Residences
Premium apartments crafted for modern city living and long-term investment.
Featured Neighbourhood
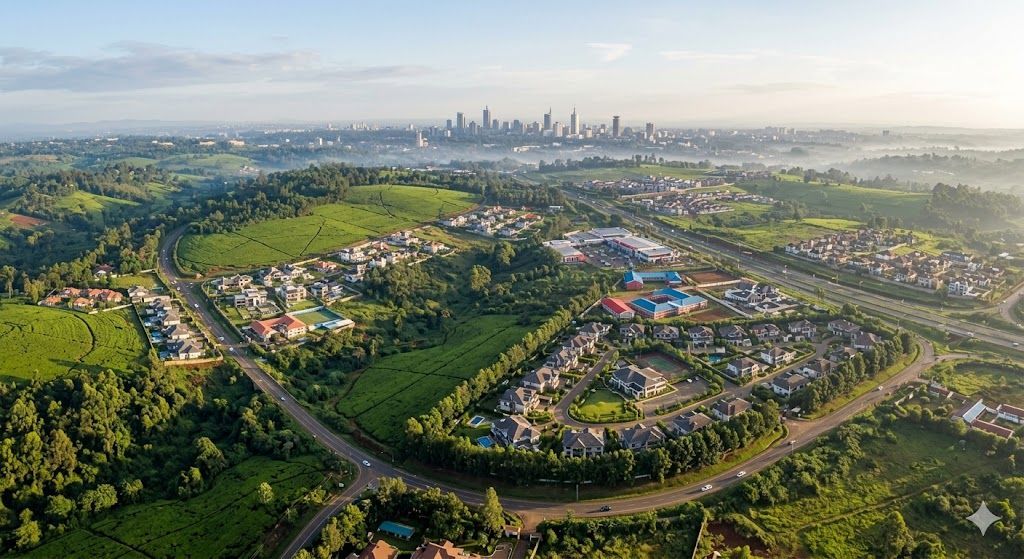
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Ongata Rongai
Affordable Family Living with Nairobi Convenience
Featured Neighbourhood
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.