Real Estate in Kenya in 2026: Still Promising, But Not Easy Money
Is Kenyan real estate still a sound investment in 2026? An honest, data-backed guide to rental yields, location realities, operating costs, and due diligence.
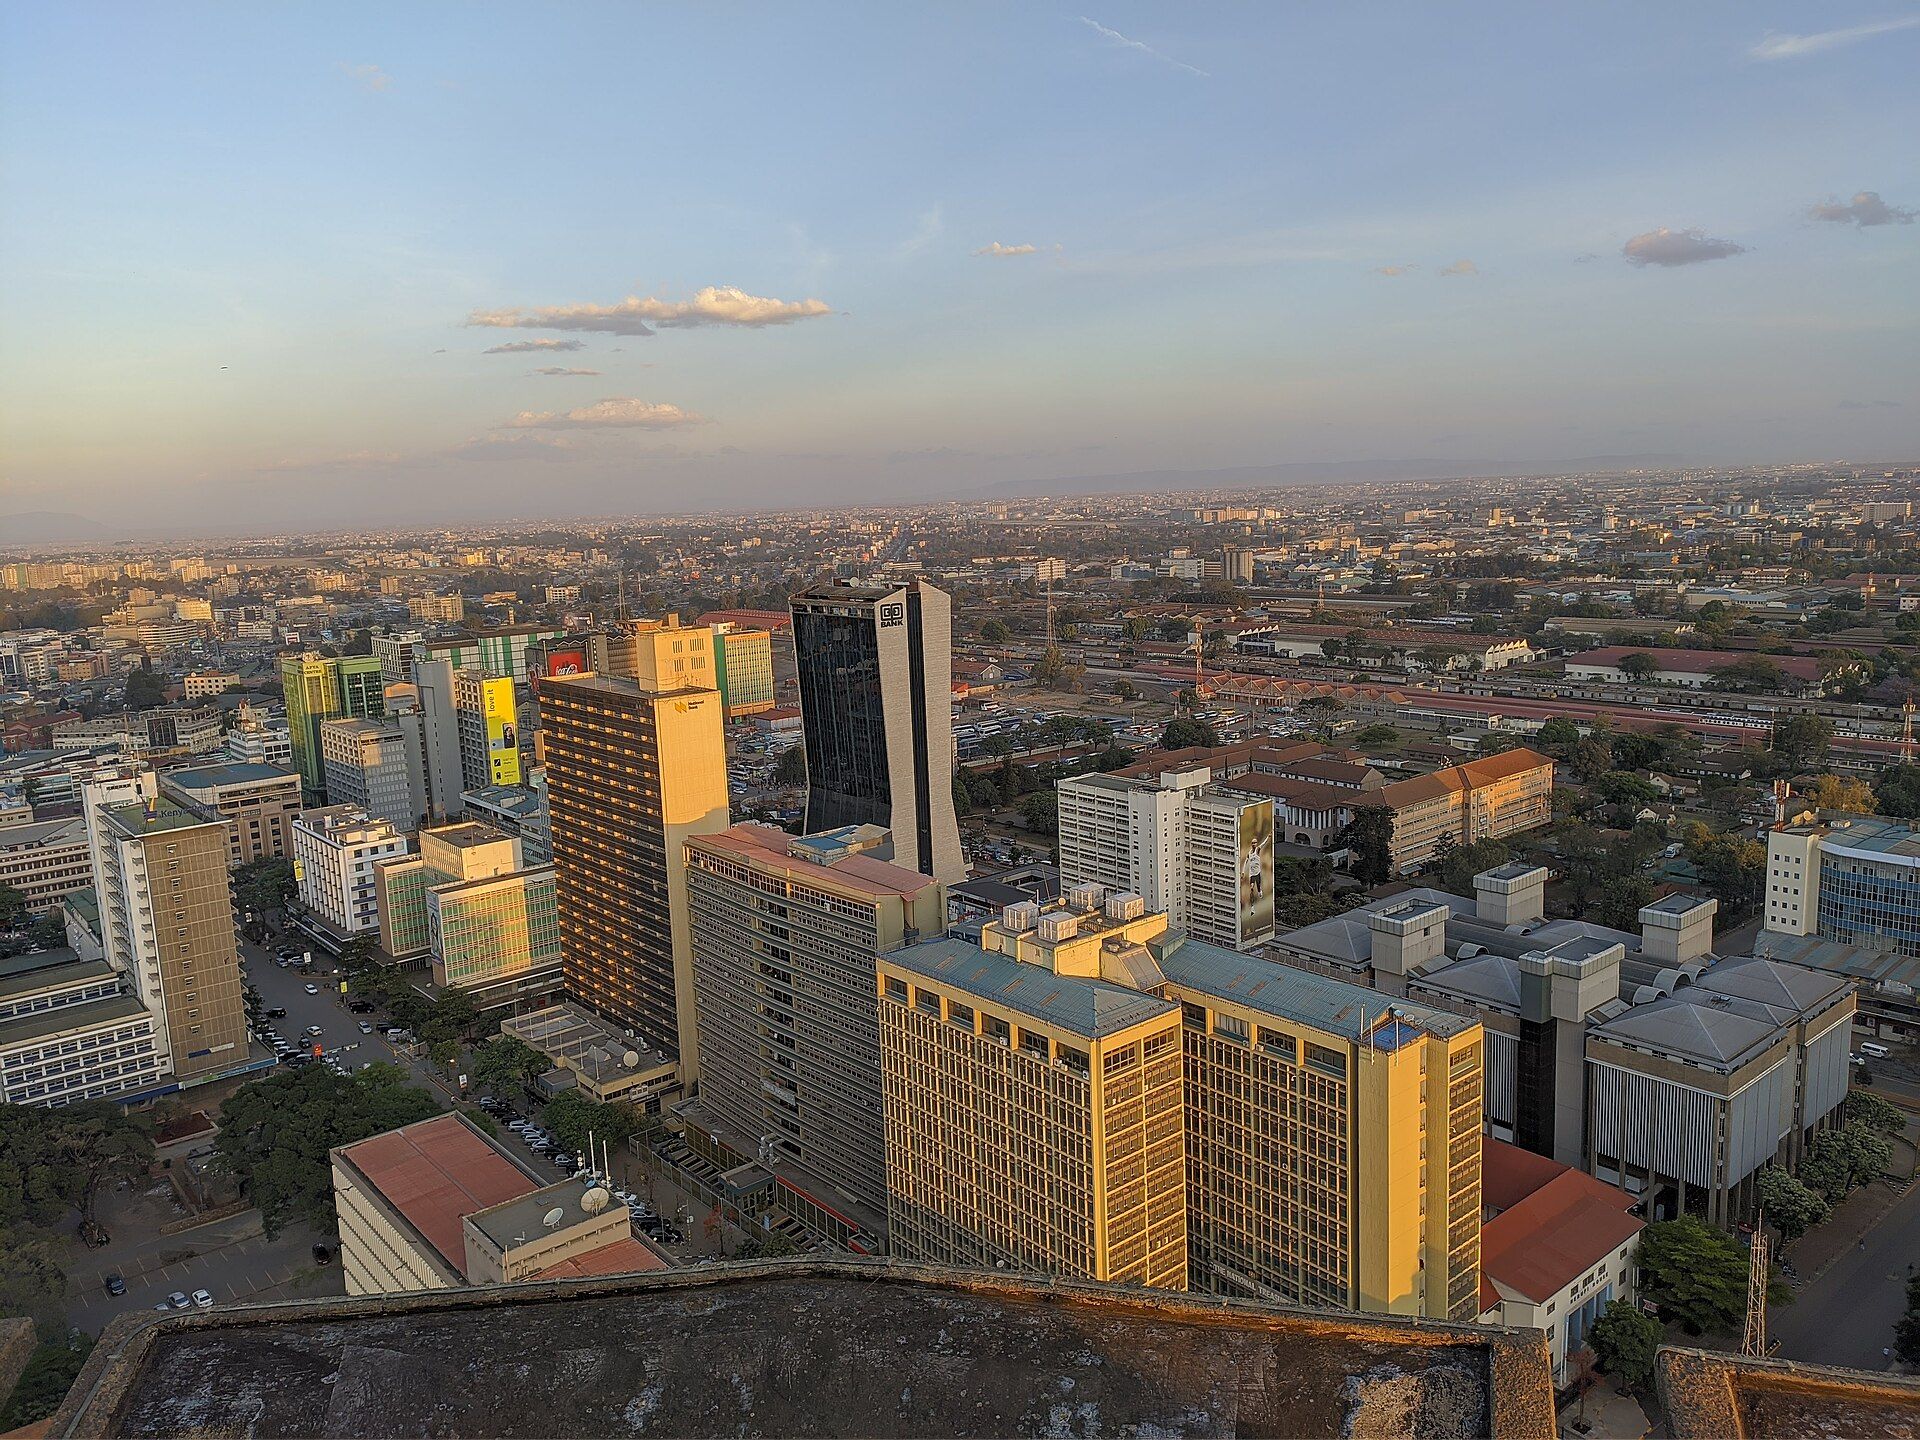
Real estate in Kenya remains a promising investment sector in 2026.
However, it is no longer a market where you can purchase any parcel of land or random off-plan unit and expect automatic wealth. For decades, the dominant Kenyan property advice was simple: buy land, wait, and sell. Sometimes that strategy paid off handsomely. Other times, investors found themselves holding undeveloped plots in remote subdivisions, paying annual land rates on empty soil while prices remained stagnant for a decade.
That speculative era has largely matured. In 2026, successful property investment depends on three interrelated disciplines: verifiable location utility, sustainable household affordability, and genuine tenant retention.
Real estate in Kenya remains fundamentally sound, but the era of easy, speculative gains is gone. Success now requires treating property as an operational cash-flow business rather than a passive lottery ticket.
The Core Question in 2026
Is property in Kenya still worth your capital in 2026? Yes. But the buyers winning today are not chasing hype. They run the numbers on actual tenant demand, budget for operating friction, verify titles independently, and purchase properties that solve real living problems for real people.
Key Market Indicators: Kenya Property Context (2025/2026)
1. What the Kenyan Property Market Looks Like in 2026
To understand property opportunities in Kenya today, one must examine macroeconomic realities rather than social media marketing. Over the past two years, the Central Bank of Kenya (CBK) initiated a measured monetary easing cycle, lowering the Central Bank Rate toward 11.25 percent. This adjustment injected liquidity into commercial banking channels, helping moderate mortgage rates from earlier peaks and lowering debt service costs for established developers.
Concurrently, the Kenyan Shilling found stability in the 128 to 132 range against the US Dollar, following sharp volatility in previous seasons. For investors and builders alike, currency stabilization has reduced the volatility of imported construction finishes, elevators, and structural steel. Inflation has also settled within the government target band of 4 percent to 5 percent, preserving baseline household purchasing power.
However, aggregate national numbers mask a critical phenomenon that property analysts describe as the apartment paradox. According to research reports from HassConsult and Knight Frank Kenya, Nairobi's residential sector has bifurcated into distinct sub-markets:
- High-density apartment nodes such as Kilimani and Kileleshwa have seen massive supply additions over the last seven years. Where developers constructed identical, commoditized 2 and 3 bedroom units without distinct lifestyle amenities, asking prices and rents corrected between 6 percent and 11 percent as landlords competed for a limited pool of qualifying tenants.
- Compact urban residences such as 1-bedroom apartments in prime business corridors like Westlands continue to demonstrate robust occupancy, generating gross yields between 7.5 percent and 8.8 percent, driven by corporate staff and executive stays.
- Low-density family enclaves including Lavington, Karen, and Runda have recorded steady price resilience for standalone townhouses, where strict zoning limits oversupply.
- Infrastructure-linked satellite towns such as Ruaka, Syokimau, Ruiru, and Juja continue to absorb middle-income commuters seeking functional living within manageable budgets.
2. Location Is More Than a Prestigious Postcode
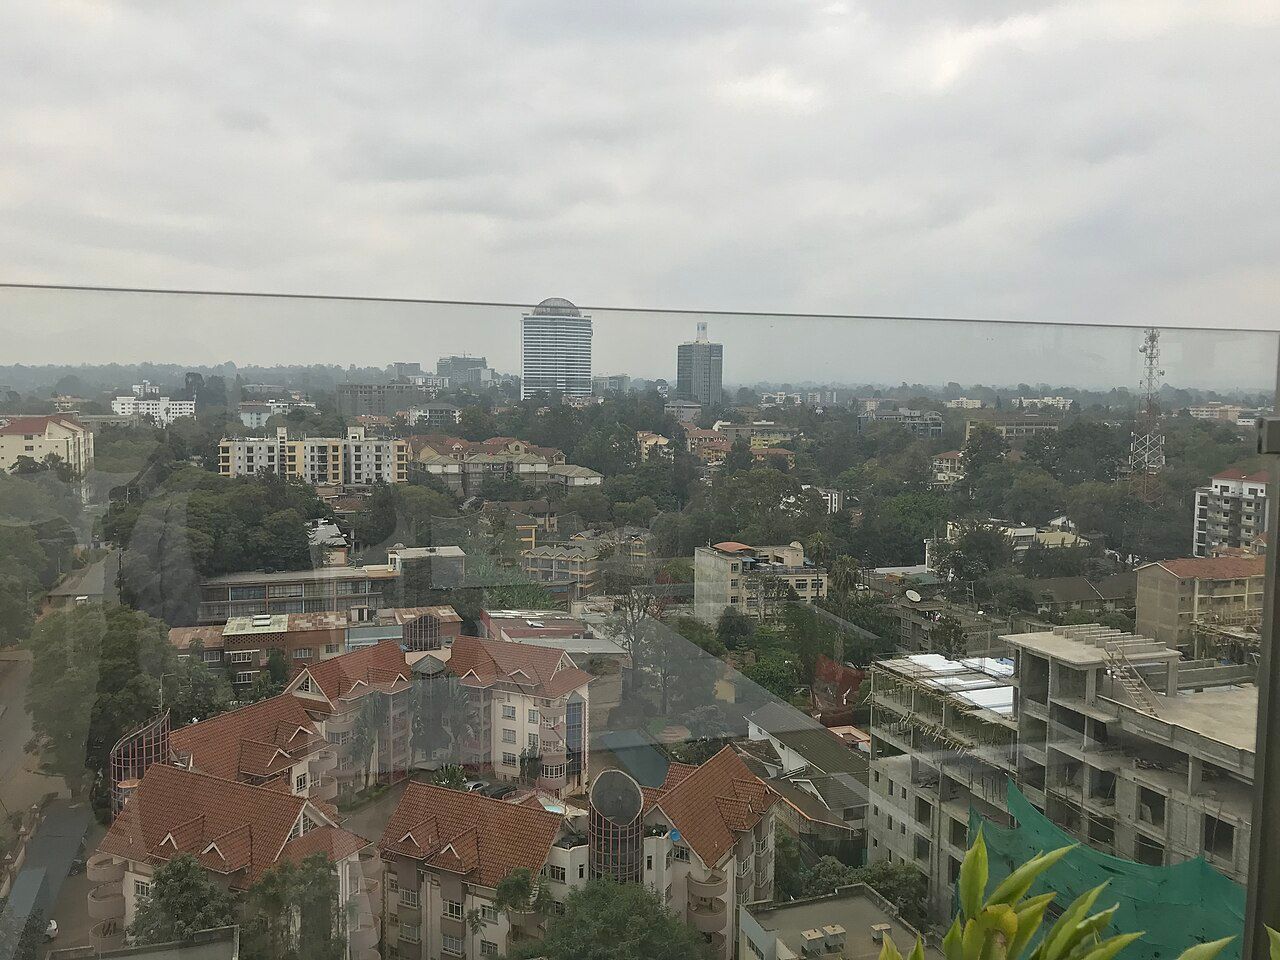
Everybody recognizes Nairobi's premier residential names: Kilimani, Kileleshwa, Westlands, Lavington, and Karen. These addresses carry undeniable prestige. However, high entry prices in mature suburbs mean that prospective rental yields can be compressed if an investor overpays at acquisition.
In 2026, the question is not simply whether a property sits inside an established postcode. The decisive question is: how easily can people actually live and work from this exact address?
Consider the day-to-day realities of urban Nairobi. Traffic congestion remains an unavoidable tax on time and energy. When transport infrastructure, bypass connections, or modern expressways reduce a daily commute, residential demand along that corridor responds rapidly. However, travel time improvements must be weighed carefully. A hypothetical commuter whose travel time drops from ninety minutes to thirty-five minutes experiences a life-changing improvement, but investors must confirm that infrastructure is physically open and operational before paying a premium for it.
The neighbourhoods that perform best over the long term are areas where daily life is already thriving:
- Proximity to major employment clusters such as Westlands, Upper Hill, and the Central Business District.
- Walking access to grocery supermarkets, pharmacies, dry cleaners, and casual dining.
- Independent water infrastructure (reliable borehole water and generous buffer storage) to insulate residents from municipal rationing.
- Secure, walkable access to reputable primary and secondary schools.
3. Affordability Determines the Real Buyer
A recurring mistake in the Kenyan property development sector over the last decade was building exclusively for an idealized buyer. Developers often designed expansive luxury penthouses targeted at high-earning diaspora investors or dollar-denominated expatriates, only to find that market segment quickly saturated.
The domestic Kenyan middle class constitutes the actual foundation of housing demand. Official employment data from the Kenya National Bureau of Statistics (KNBS) demonstrates that formal salaries have grown at a measured pace, while family budgets face elevated school fees, healthcare costs, and statutory deductions. Consequently, an apartment that commands an asking price of KSh 25 million sits far beyond the financing capacity of most local salary earners.
The properties experiencing consistent liquidity and transaction volume in 2026 are those priced for economic reality:
- Smarter, space-efficient floor plans: A well-planned 56-square-metre 1-bedroom apartment or an 85-square-metre 2-bedroom unit that eliminates wasted corridor space.
- Accessible capital thresholds: Units priced between KSh 6.5 million and KSh 12 million, where buyer deposits and installment plans remain within realistic reach.
- Realistic payment flexibility: Milestone-based payment schedules tied to certified construction phases rather than aggressive short-term cash demands.
Affordability Is Not Inferior Quality
Affordable does not mean poorly built or cheap. In practical terms, affordability means the financial arithmetic works comfortably for the end-user. When an apartment is priced within the reach of local professionals, you never have to depend on market miracles to keep it occupied.
4. Rental Demand Is Not the Same as Rental Profit
Because purchasing a home outright requires substantial capital, the rental market serves as the true economic engine of Kenyan real estate. Tens of thousands of young professionals, growing families, university faculty, and regional business consultants require quality rental housing across Nairobi every month.
However, prospective landlords frequently confuse gross rental collection with net investor profit. A property can remain fully occupied and yet generate disappointing net returns if operational friction is ignored at the time of purchase.
When evaluating an investment property, you must budget for five recurring financial frictions:
1. Vacancy Allowance: Even in desirable neighbourhoods, tenant turnover occurs. Prudent financial planning requires setting aside at least one month of vacancy per year (an 8.33 percent allowance) to account for lease transitions and marketing periods.
2. Estate Service Charges: Maintaining 24-hour manned security, common area lighting, elevator maintenance service contracts, and backup generator fuel requires monthly contributions. Learn more about how service charges work in Kenya and who pays them.
3. Letting and Property Management Fees: Professional managing agents typically charge between 8 percent and 10 percent of collected rent to screen tenants, collect dues, manage leases, and resolve maintenance emergencies.
4. Routine Repairs and Sinking Fund: Repainting walls between tenants, servicing tap cartridges, replacing light fixtures, and maintaining joinery requires a continuous maintenance reserve.
5. Statutory Taxes: The Kenya Revenue Authority levies Residential Rental Income Tax at a simplified rate of 7.5 percent on gross residential rent received, payable monthly via the iTax platform. Learn the full tax breakdown in our complete guide to property taxes, stamp duty, and CGT in Kenya.
5. Transparent Financial Example: A Practical Rental Yield Breakdown
To understand the difference between gross marketing yield and true net cash return, examine the following transparent, illustrative calculation for a modern 1-bedroom apartment in an established Nairobi node such as Westlands or Kilimani.
This example uses clear, hypothetical figures to illustrate the calculation process. It does not represent a promised return or a guaranteed market average.
| Financial Parameter | Illustrative Amount (KES) | Notes / Calculation Basis |
|---|---|---|
| Purchase Price | KES 8,500,000 | Baseline all-inclusive acquisition cost |
| Anticipated Monthly Rent | KES 60,000 | Unfurnished long-term market expectation |
| Gross Annual Rent (100% Occupancy) | KES 720,000 | KES 60,000 x 12 months |
| Gross Rental Yield | 8.47% | (KES 720,000 / KES 8,500,000) x 100 |
| Vacancy Allowance (1 Month) | - KES 60,000 | Realistic 8.33% turnover buffer |
| Effective Gross Rent Collected | KES 660,000 | Actual cash collected in bank |
| Annual Estate Service Charge | - KES 72,000 | KES 6,000 monthly landlord contribution |
| Property Management Commission | - KES 52,800 | 8% of collected rent (KES 660,000 x 8%) |
| Annual Maintenance Reserve | - KES 30,000 | Repainting, locksets, plumbing upkeep |
| KRA Residential Rental Income Tax | - KES 49,500 | 7.5% statutory rate on KES 660,000 |
| Total Annual Operating Deductions | - KES 264,300 | Sum of vacancy, service charge, fees, tax |
| Net Operating Income (NOI) | KES 395,700 | Cash flow before financing |
| Net Operating Yield | 4.66% | (KES 395,700 / KES 8,500,000) x 100 |
Notice what this calculation reveals. While the brochure advertises a headline gross rental yield of 8.47 percent, the actual cash delivered to the investor's bank account after legitimate operating expenses, turnover, and statutory tax is 4.66 percent.
Furthermore, this figure represents net operating yield before any commercial mortgage interest, bank facility appraisal fees, or upfront conveyancing legal costs. If you finance the acquisition using a commercial bank mortgage at 14 percent interest, debt service will absorb a significant portion of that operating surplus. That is why understanding your numbers before signing is indispensable.
Net Operating Yield
The annual net cash flow generated by a property after deducting vacancy losses, estate service charges, management commissions, maintenance reserves, and property taxes, divided by the total acquisition cost. Unlike gross yield, net operating yield reflects the genuine cash return an investor receives.
6. Think Like a Tenant Before Buying for Investment
If your intention is to purchase a property for rental income, you must discipline yourself to evaluate the building through the eyes of a discerning tenant rather than an emotional buyer.
Tenants in Nairobi care very little about grand architectural statements or golden fixtures in the lobby. What keeps tenants in place month after month are practical amenities that eliminate daily life frustration:
1. Uninterrupted Water Security: Municipal water rationing is widespread across Nairobi. A development that features a high-capacity licensed borehole, commercial filtration systems, and substantial rooftop storage tanks will retain tenants when neighbouring buildings run dry.
2. Full Backup Power Redundancy: An automatic standby generator that powers only the lobby and elevators is insufficient for professionals working remotely. Tenants actively seek properties where backup power is reticulated into their apartment to run laptops, routers, refrigerators, and lighting during power outages.
3. Acoustic Insulation and Privacy: High-density urban living requires solid brickwork or double-leaf partition walls. Units with paper-thin plasterboard walls where every corridor conversation echoes quickly suffer high turnover.
4. Functional Kitchens and Laundry Balconies: In Kenya, cooking habits and laundry drying require dedicated, well-ventilated spaces. Properties featuring enclosed utility yards or practical balcony laundry connections lease faster than units with compromised layouts.
5. Dedicated, Secure Parking: In developments with limited parking ratios, disputes over parking bays create constant tenant friction. Confirm that your unit holds an allocated, registered parking bay.
7. The Due Diligence Checks to Complete Before Committing Money
Too many property transactions in Kenya begin with excitement and end in litigation because the buyer skipped preliminary due diligence. Before any deposit or commitment fee leaves your account, complete the following rigorous verification process:
- Official Title Search: Instruct your independent conveyancing advocate to perform an official title search via the Ministry of Lands ArdhiSasa digital registry or the local land office. Verify registered ownership, remaining leasehold term, and ensure no encumbrances, bank charges, or court cautions exist against the title.
- Sectional Properties Act 2020 Compliance: When buying an apartment, verify that the developer has prepared and registered a formal sectional plan. Under Kenyan law, sectional title deeds grant the buyer individual freehold or long-term leasehold title to their unit, along with proportionate co-ownership in the common property.
- County Planning and Environmental Approvals: Confirm that the development holds approved architectural and structural drawings from the Nairobi City County (or relevant county government), alongside an Environmental Impact Assessment (EIA) license from NEMA and registration with the National Construction Authority (NCA).
- Developer Track Record Inspection: Do not rely on digital 3D renderings alone. Visit earlier developments completed by the same developer. Inspect the quality of concrete finishes, speak directly to current residents, and ask whether the management company delivers responsive service.
- Milestone-Based Escrow Payments: For off-plan purchases, your sale agreement must link installment payments to independent architect certificates confirming actual construction progress (such as foundation completion, structural framing, roofing, and interior finishes), rather than arbitrary calendar dates.
Sectional Title Deed
A legally recognized certificate of ownership issued under the Sectional Properties Act 2020 that grants the purchaser absolute legal title over their individual apartment, flat, or townhouse unit, together with an undivided share in the common property (such as land, driveways, roofs, and security installations).
8. A Practical Property Investment Checklist for 2026
Before committing your capital to any residential opportunity in Kenya, run through this six-point evaluation framework:
1. Clear Strategic Purpose: Are you purchasing an primary residence for your family, a long-term buy-to-let apartment for steady rental cash flow, or a short-stay rental property? Each objective requires different locations, finishes, and layout criteria.
2. Comprehensive Capital Budget: Have you budgeted for legal conveyancing fees (1.5 percent to 2 percent plus VAT), urban stamp duty (4 percent), professional valuation fees, utility meter deposits, and initial service charge floats?
3. Micro-Location Audit: Have you physically visited the location during peak traffic hours on a weekday? Is road access paved, well-lit, and secure?
4. Tenant Demographics: Who is the specific target tenant for this unit? What is their monthly budget, and do competing developments nearby offer similar features for less?
5. Operational Friction Allowance: Does the net operating yield remain attractive after deducting realistic vacancy, service charges, management fees, maintenance reserves, and rental income tax?
6. Exit and Liquidity Strategy: If your personal financial circumstances change in three years, how easily can this unit be sold or re-let? Properties with sectional titles and accessible price points enjoy far higher secondary market liquidity.
Key Takeaways
- 01.Kenyan property in 2026 rewards operational cash flow and disciplined research over speculative land banking.
- 02.Macroeconomic conditions have improved with CBK interest rate reductions and currency stability, but apartment supply remains highly segmented across sub-markets.
- 03.Gross rental yields in Nairobi range from 7 percent to 8.8 percent, but realistic net operating yields average between 4.5 percent and 6.0 percent after accounting for vacancy, service charges, management commissions, and taxes.
- 04.Tenant retention depends on reliable infrastructure: uninterrupted borehole water, full backup generators, functional kitchens, and responsive building management.
- 05.Independent legal due diligence, official search verification on ArdhiSasa, and compliance with the Sectional Properties Act 2020 are essential before paying any deposit.
9. What This Means for Different Types of Buyers
Because different buyers face different financial realities, here is how market conditions in 2026 translate into practical decisions:
For First-Time Homebuyers
Do not stretch your family finances to purchase an oversized property in a suburb you cannot comfortably maintain. Focus on functional design, manageable commute times to your workplace, and stable monthly service charges. A smaller, well-located 2-bedroom home in a master-planned community often offers superior peace of mind compared to an expensive standalone build that drains your monthly savings.
For Buy-to-Let Investors
Focus strictly on net operating yield, tenant turnover speed, and building management quality. In the current market, compact 1-bedroom and 2-bedroom apartments near major employment nodes such as Westlands or Kilimani consistently deliver higher occupancy and easier management than multi-bedroom luxury units.
For Family Homeowners
Prioritize compound security, green communal spaces, and proximity to reputable schools. In established residential zones like Lavington or Karen, controlled density preserves family lifestyle and long-term resale stability.
For Diaspora Buyers
Never conduct property transactions through informal family arrangements or unvetted brokers. Work exclusively with an independent conveyancing advocate registered in Kenya, mandate third-party site verification, and purchase from established developers offering formal milestone contracts. For remote buyers, exploring verified developments like Luminara Residency in Westlands or Belgravia Place in Kileleshwa provides clear documentation and construction accountability.
Conclusion: The Opportunity Is Real, But the Numbers Must Work
Real estate in Kenya remains one of the most resilient wealth preservation vehicles in East Africa. The country's young population, rapid urbanization, and position as a regional commercial hub provide enduring structural demand for well-built homes.
However, the easy money stories are mostly behind us. Winning in today's property market requires patience, local insight, realistic calculations, and honest due diligence.
Before committing your hard-earned savings, run the numbers on affordability, verify the title documents independently, and inspect the physical infrastructure. If you treat property as a serious business and partner with knowledgeable advisors, the opportunities in 2026 remain genuinely compelling.
If you are evaluating residential property in Kenya and would like honest, accompanied guidance on high-performing developments, contact our advisory team at Zuri Estates Contact or explore our curated portfolio of developments and residences.
Verified Sources & References
Official & Peer ReviewedCentral Bank of Kenya (CBK) Monetary Policy Committee
“Monetary policy decisions lowering the Central Bank Rate toward 11.25 percent to support domestic credit expansion while anchoring inflation within the target corridor.”
Kenya National Bureau of Statistics (KNBS) Economic Survey
“Annual macro-economic and household expenditure reporting documenting real household income trends, inflation moderation, and urbanization patterns.”
HassConsult Real Estate Property Price & Rental Index
“Quarterly tracking of asking prices, rental movements, and gross rental yields across 18 Nairobi suburbs and 14 satellite towns.”
Knight Frank Kenya Market Update
“Research report detailing prime residential occupancy, commercial sector performance, and shifting investor allocations in Nairobi.”
Ministry of Lands and Physical Planning (Sectional Properties Regulations)
“Statutory guidelines governing the mandatory transition from long-term sub-leases to individual sectional title deeds under the Sectional Properties Act 2020.”
Antony Baragu
Real estate strategist
Antony specializes in strategic acquisitions across Nairobi's most established residential enclaves, including Kilimani, Kileleshwa, and Westlands. His analytical approach and detailed understanding of off-plan developments assist buyers and investors in evaluating property specifications, payment structures, and market timing.
Zuri Estates Team
Property Advisory & Client Coordination
This article has been reviewed by Zuri Estates Team to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods

Westlands · 23 Mogotio Road, Westlands, Nairobi
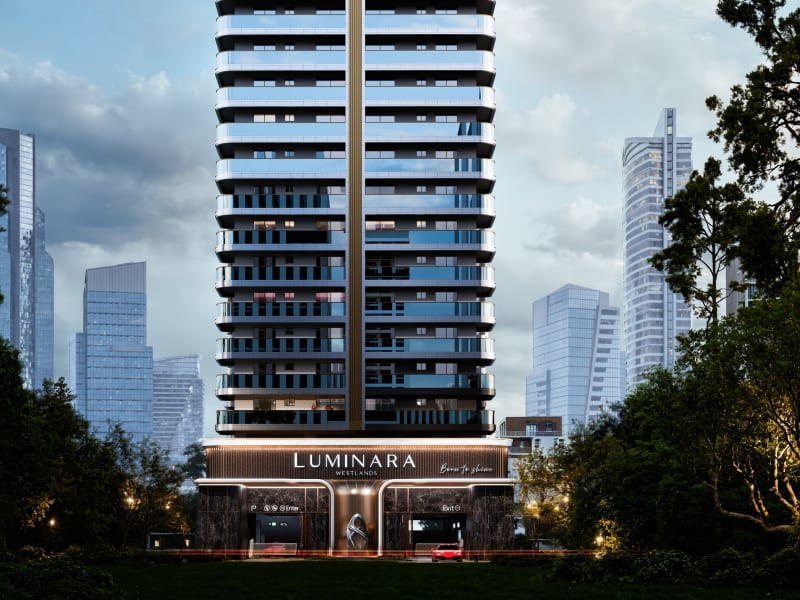
Luminara Residency Westlands
Hotel-inspired luxury twin towers on Mogotio Road featuring panoramic skyline living, rooftop infinity pool, and high-yield returns.

Westlands · 5 Vihiga Road, Kileleshwa, Nairobi
Belgravia Place
Refined 1, 2 and 3-bedroom residences with rooftop padel court and heated sky pool

Featured Neighbourhood Suburb
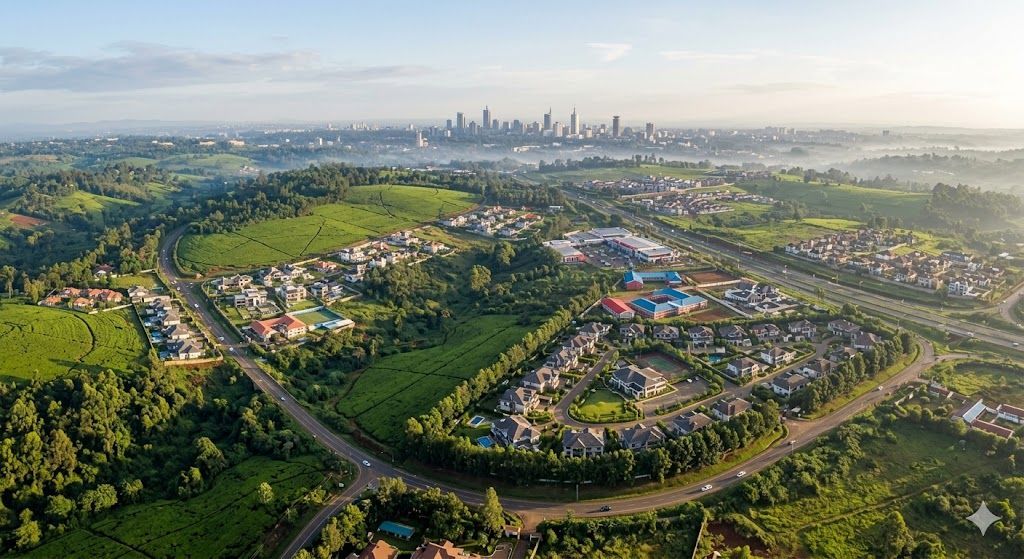
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.
Featured Neighbourhood Suburb
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood Suburb
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.
Featured Neighbourhood Suburb
Lavington
One of Nairobi’s most prestigious residential neighbourhoods, known for luxury homes, green surroundings and family living.